Showing posts with label Investment: Education. Show all posts

Monday, November 21, 2022

162 An Experiment: Ray Dalio's All Weather Portfolio using Malaysia Unit Trust 实验:用马来西亚信托基金尝试重建达里欧全天候资产组合

162 An Experiment: Build Ray Dalio's All Weather Portfolio using Malaysia Unit Trust 一个实验:用马来西亚信托基金尝试重建达里欧全天候资产组合


Who is Ray Dalio?

Raymond Thomas Dalio is an American billionaire investor and hedge fund manager, who has served as co-chief investment officer of the world's largest hedge fund, Bridgewater Associates, since 1985. (Source: Wikipedia)


What makes Ray Dalio to create All-weather Portfolio?

The principles behind All Weather relate to answering a deceptively straightforward question explored by Ray with co-Chief Investment Officer Bob Prince and other early colleagues at Bridgewater — what kind of investment portfolio would you hold that would perform well across all environments, be it a devaluation or something completely different? (Source:- The All Weather Story)


What is the breakdown of All Weather Portfolio?

Weight Investment Themes
30.00 % U.S., Large Cap
40.00 % Bonds, U.S., Long-Term
15.00 % Bonds, U.S., Intermediate-Term
7.50 % Gold
7.50 % Commodity, Broad Diversified


Breakdown the All Weather Portfolio using Malaysia Unit Trust

In fact, if investors have stock trading account that can trade US stocks, he can actually build the portfolio using US' ETF (like VTI etc).

But let say I am more comfortable with local unit trust, can I duplicate a similar portfolio. Let's try to see each category. I will use info from FundSuperMart Malaysia and Morningstar Malaysia.

U.S., Large Cap

In Malaysia, there are two US Equity funds available to retail investors.
  • Manulife Investment U.S. Equity Fund - MYR Class
  • RHB-GS US Equity Fund

Bonds, U.S., Long-Term and Bonds, U.S., Intermediate-Term

For local unit trust, there is no retail unit trusts invested in US bonds. So, let's replace with local unit trusts. Below is the one I always use.
  • Amanahraya Unit Trust Fund
  • Amanahraya Shariah Trust Fund

Gold

There are altogether four funds in this category, but only the below two are more than 10 years old.
  • RHB Gold And General Fund
  • Precious Metals Securities

Commodity, Broad Diversified

For commodities, we search using the word "resources".
  • Manulife Global Resources Fund
  • RHB Resources Fund
I am going to pick one or two funds from each category. (Warning: This selection is based my personal preference. It is not objective. Please do not follow!)

U.S., Large Cap:- Manulife Investment U.S. Equity Fund - MYR Class

Bonds, U.S., Long-Term and Bonds, U.S., Intermediate-Term:- Amanahraya Unit Trust Fund, Amanahraya Shariah Trust Fund

Gold:- RHB Gold And General Fund

Commodity, Broad Diversified:- Manulife Global Resources Fund


The Returns of Individual Funds

The total returns and annualised returns of each funds are as below chart. I use Chart Center from FundSuperMart Malaysia.


Apparently, if I simply invest in Manulife Investment U.S. Equity Fund - MYR Class, my annual returns for the past 10 years is 14.39%. This is consider very good especially when we consider the recent drop of roughly 25%. However, the volatility — at 22.42% — is very high too.

If I am very kiasi, and were to fully invest in bonds — namely Amanahraya Unit Trust Fund and / or Amanahraya Shariah Trust Fund — my returns 2.79% & 1.94% only. Actually the returns were dragged down because of the effect of US rising interest rate.


How about combined them into a portfolio? The All Weather Portfolio!

For this, I use Portfolio Simulator from FundSuperMart Malaysia. The assumptions are
  • Initial Investments:- RM100,000
  • Backtest Period: - 10-Yr
  • Rebalancing:- Quarterly
  • Wholesale Funds:- No
Portfolio 1:-
  • 100% Manulife Investment U.S. Equity Fund - MYR Class

Portfolio 2:-
  • 30% Manulife Investment U.S. Equity Fund - MYR Class
  • 30% Amanahraya Shariah Trust Fund
  • 25% Amanahraya Unit Trust Fund
  • 7.5% RHB Gold And General Fund
  • 7.5% Manulife Global Resources Fund

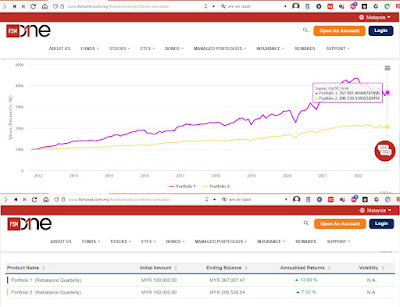
The results are


The annualised returns for Portfolio 1 is 13.89% (RM100,000 becomes RM367,007). The annualised returns for Portfolio 2 is 7.52% (RM100,000 becomes 206,538).

Portfolio 2 is significantly lower than Portfolio 1, but the chart is much smoother too. Considering the current market situation (equity and bonds tanked together), I think Portfolio 2's returns is very good and not so stressing.


The largest drawdown during the current market crash

From experience, investors always think they are aggressive investors who can tahan market crash, but in fact they are not. See -5%, still can tahan. See -10%, a little bit uneasy. See -15%, maybe cannot tahan liao. See -20%, sell sell sell.

So, let's see how much was the largest drawdown during the current market crash.


The calculation:-


Comparatively, I think losing -6% is less stressful than losing -21%.


Small Conclusion

I think this Ray Dalio All Weather Portfolio is very suitable for investors who are seeking higher returns with fairly lower volatility. Most important of all, the portfolio can absorbs unexpected shocks like stock market crash. In the normal situation, bonds will rise when stock market go lower. Likewise, gold and commodities — which has inverse relationship with equity — will also help to lift the portfolio value.

Reminder:- I do not currently own such All Weather Portfolio.


////////// SEPARATOR 分割线 /////////


请问谁是达里欧先生啊?

雷蒙德·托马斯·达利奥(英語:Raymond Thomas Dalio,1949年8月8日)出生于纽约,现居康乃狄克州费尔菲尔德县,是美国对冲基金经理、慈善家。雷·达利奥是桥水基金公司的创始人兼首席執行官,而橋水基金於2013年被列為全世界最大的避險基金公司。(来源:维基百科)


达里欧先生为何要找寻这个全天候投资组合啊?

全天候投资组合背后的原则其实就是为了回答这些人的一个非常简单明了的问题。这些人是达里欧、co-Chief Investment Officer Bob Prince、以及桥水基金早期同事们。这个问题就是 — 怎样的组合才是你想要持有的组合,即任何环境下(货币贬值也好、其他情况也好)都有好的表现的组合? (自己翻译。有错请指教。Source:- The All Weather Story)


全天候投资组合由什么合成啊?

比重  投资主题
30.00 % 美国大型股
40.00 % 美国长期债券
15.00 % 美国短期债券
7.50 % 黄金
7.50 % 一般大宗商品


试试看用本地信托基金合成这个全天候投资组合咧

其实捏,如果投资者有股票投资户头,他们就可以直接买入美国 ETF 来配置这样的全天候投资组合滴。

但是,万一我比较喜欢本地信托基金,可不可以配置接近接近的组合呢?我们一样一样来看。我会用 FundSuperMart Malaysia 和 Morningstar Malaysia 的网站来找资料。

美国大型股

在本地,只有两个美国基金是开放给所有投资者的。
  • Manulife Investment U.S. Equity Fund - MYR Class
  • RHB-GS US Equity Fund

美国长期债券、美国短期债券

本地信托基金,没有专门投资美国债券的。所以我用本地基金来代替。以下是我常用的。
  • Amanahraya Unit Trust Fund
  • Amanahraya Shariah Trust Fund

黄金

这个组别里面有四个基金,但是只有两个基金有十年历史。
  • RHB Gold And General Fund
  • Precious Metals Securities

一般大宗商品

大宗商品,我们用关键字 "resources"。
  • Manulife Global Resources Fund
  • RHB Resources Fund
现在啊,我从每个组别选一两个基金。 (提醒!以下所选的全部是根据我的喜好,并不是客观的分析。请不要贸贸然跟喔!盈亏自负!)

美国大型股:- Manulife Investment U.S. Equity Fund - MYR Class

美国长期债券,美国短期债券:- Amanahraya Unit Trust Fund, Amanahraya Shariah Trust Fund

黄金:- RHB Gold And General Fund

一般大宗商品:- Manulife Global Resources Fund


各个基金的回酬

各个基金的回酬如下图所示。我用 FundSuperMart Malaysia 的 Chart Center 。


很明显的,如果我单押 Manulife Investment U.S. Equity Fund - MYR Class ,我的10年复利回酬是 14.39%。以现在的环境,美股跌了大概25%,还有这样的回酬算是非常了不起的。可是啊,波动率 — 22.42% — 也是很高捏。

假设我是怕死的投资者,全部单押债券的话 — Amanahraya Unit Trust Fund 或者 Amanahraya Shariah Trust Fund — 我的回酬只有区区 2.79% & 1.94% 罢了。这样的回酬其实是被美国升息的影响拉低的。


啊,如果把他们做成组合会怎样?全天候投资组合喔!

现在就要用到 FundSuperMart Malaysia 的 Portfolio Simulator 。所做的假设如下:-
  • 初始投资额 Initial Investments:- RM100,000
  • 回测期限 Backtest Period: - 10-Yr
  • 再平衡 Rebalancing:- Quarterly 每季
  • Wholesale Funds:- No
组合 1:-
  • 100% Manulife Investment U.S. Equity Fund - MYR Class

组合 2:-
  • 30% Manulife Investment U.S. Equity Fund - MYR Class
  • 30% Amanahraya Shariah Trust Fund
  • 25% Amanahraya Unit Trust Fund
  • 7.5% RHB Gold And General Fund
  • 7.5% Manulife Global Resources Fund

成绩来咯


组合1的复利回酬为 13.89% (RM100,000 滚成 RM367,007). 组合2的复利回酬为 7.52% (RM100,000 滚成 206,538).

组合2的回酬明显低于组合,但整条线图明显平顺很多,代表着波动比较低。依目前的市场来说组合2的回酬亮眼又比较没有压力。


本波股市下跌最大跌幅

倚老卖老,投资者总是高估自己是激进型投资者,即可以忍受市场暴跌,事实却又很残忍。当他们看到 -5%,还可以顶。看到 -10%,有一点紧张了。看到 -15%,应该顶不顺了。看到 -20%,快点卖,天要塌了。

那就让我们来看看此次股市下跌的跌幅。


计算如下:-

相比而言,个人相信亏损 -6% 的压力应该远远低过亏损 -21%。


小总结

个人认为达里欧的这个全天候投资组合非常适合那些要稍高回酬、稍低风险的投资者,比如退休人士。尤为重要的,此组合能承受股市暴跌的震荡。在正常的情况下,股市下跌、债券会上。黄金以及一般大宗商品也能提振组合的价值,因为这两种与股市也是呈相反的联动。


再次提醒。本人目前没有全天候投资组合!

Thursday, September 7, 2017

127 Some ways to save children's education funds in foreign currencies


Some ways to save children's education funds in foreign currencies

为孩子教育基金储蓄外币的几种方法

For parents that intent to send their children to study oversea, the ultimate currency to be used would be the target country's currency. The conventional method to plan education fund is to save in RM, and then convert them as their child is ready to go oversea. That is to save over a span of 10, 15 or 18 years. 对于想送孩子出国留学的父母们,最终要用到的货币还是当国的货币。最传统的做法是全部储蓄马币,然后在孩子准备出国的时候兑换当国货币。这样大概要储蓄10,15或18年。
That worked fine for many parents for many years. But in 2014, many parents felt the pain when USD appreciated against MYR, suddenly, from RM3.30 to RM4.50 to a dollar. That was a sudden increased of 40%. God knows how many children's education were delayed or diverted elsewhere. 那个方法确是行得通。但在2014年,美元兑马币忽然从3.30升高至4.50兑一美元,这情况让许多父母不知所措。天晓得多少学子必须延迟大学教育或是易地就学。
-
We know it is hard to predict currency exchange rate. But today's parents actually can better prepared their children's education funds. They can actually start saving part of the money in foreign currencies. For example, a parent may save in a combination of RM, USD and SGD. When the day come, he may then decide which currency to use to pay the college fees. If parents has intentions to save in foreign currencies, some ways I can think of are as below. 货币兑换率确是不易预测。今天的父母能做的就是做好预备。父母们可以为孩子们一开始就储蓄外币。例如,父母们可以储蓄马币,美金和新币。当孩子要上大学时,再来决定要使用那个货币。若是父母们确有这样的意愿的话,以下是我可以想到的几种方法。
a) Convert RM to foreign currency and keep at home. This must be the easiest, but also the most dangerous and the least productive. By easiest I mean a parent may just drop by any money changer when he has the money and the rate is attractive. By least productive I mean the foreign currency will not be earning any interest. By dangerous I mean it is most susceptible to theft or even termite destruction. a) 兑换外币收藏在家。这必定是最容易的方法,却是最危险也是最没有生产力的方法。最容易是因为父母只要有钱且兑换率划算,即可到货币兑换商那儿兑换外币。最没有生产力是因为钱不会生钱啊。最危险则是因为钱收在家里容易遭盗窃,甚至遭白蚁蛀食。
b) Convert RM to foreign currency and keep in foreign currency account at banks. This is an upgrade version of a). At least in the banks, the money is more secured, and the banking system has the track record of history of deposits. This makes it easy when the money wants to be remitted to pay for college fees. b) 兑换外币收在银行。这是a)的升级版。把钱收在银行当然更加妥当,且银行将有所有的存储记录,这样当要汇钱出国的时候就容易许多。
c) Directly save in foreign currency in that particular country. This apparently only applicable for parents has accounts overseas, maybe they have employment or business there. Like many parents in JB work in Singapore, so naturally they have savings account in Singapore. So they can keep the money there for their children. However, if the money is just sitting in FD, the interest would be a miserable 1% perhaps. Here again, parents has to look for better way to grow the money. c) 直接把外币收在当国。这比较适合在国外有银行户头的父母们,或许她们在当国有工作或者生意之类的情况。比如在新山的父母们挺多是在新加坡工作的,所有自然而然会在新加坡拥有储蓄户头。那他们就可以把钱留在那里。但是如果钱只是留在定期存款的话,利息就只要区区的1%左右。父母们应该寻找更好的生钱方法。
d) Save in foreign currency through offshore insurance. For parents that work in Malaysia, one alternative would be to save through offshore insurance. Companies like Investor's Trust SPC, Hansard International, Premier Assurance Group and Archipelago Insurance do offer such policies. Policies holders would simply pay their premium monthly over a span of 10, 15 or 20 years. d) 透过离岸保险储蓄外币。对于在本地工作的父母,其中一个选择就是透过离岸保险来储蓄。离岸保险公司如 Investor's Trust SPC, Hansard International, Premier Assurance Group 以及 Archipelago Insurance 都有这类保单。保客只需每月供款10,15或20年即可。
e) Save in foreign currency through Phillip Global Wrap Account (PGWA). Another alternative for parents working in Malaysia would be to use Phillip's investment account - PGWA. Take for example of parents that work in Singapore. They can invest in PGWA to grow their money. They may not have the time during office hour to go to the bank to inquire about investment matters. But in view that PGWA account opening is in Malaysia, parents can actually approach us during weekends, holidays or off-days. e) 透过Phillip Global Wrap Account (PGWA)储蓄外币。另一个选择是透过辉立公司的投资户头PGWA来达到目的。例如在新加坡工作的父母们即可把他们在新加坡的储蓄投资在PGWA来达到资本增长的目的。一般上这些父母们无暇在工作时间到银行办理投资事宜,但因为PGWA乃是在本地开户,所有父母们可以趁着周末、假日或是休息日来办理。
f) Invest in unit trust funds that accepts foreign currency. There are some funds available locally where the fund house accept other currencies on top of the RM. We called this "multi-currency funds". Example are Affin Hwang SGD Income Fund (MYR Class) and Affin Hwang SGD Income Fund (SGD Class). In this example, client can invest using RM or SGD. Since this fund invest in Singapore securities, client's investment will grow in tandem with Singapore's economy. And if client were to invest using SGD, he can avoid any negative impact to his total return due to exchange rate. f) 透过投资在接受外币的信托基金。本地有些基金是有接受马币以外的货币的。我们称之为“多元货币基金”。例如Affin Hwang SGD Income Fund (MYR Class) 以及 Affin Hwang SGD Income Fund (SGD Class)。顾客可以选择一马币或新币来进行投资。因此基金乃是投资于新加坡相关证券,顾客的投资可跟随新加坡的经济成长。而若同时是以新币投资的话,顾客可避开货币间兑换率对回酬的负面影响。
Through d) and e), clients has a way to participate in destination country's growth. Example is if client want to send their children to Australia, they may buy AUD policies or invest in Aussie dollar unit trust funds. This way, their AUD money will grow in tandem with Australia's economy and inflation rate. 透过d)和e)这两个方法,父母们即可参与当国的成长机会。比如顾客打算送孩子到澳洲读书,那他们可以购买澳元保单或是澳元信托基金。如此,他们的澳元资产将随着澳洲的经济增长而赢过当地的通货膨胀。
So those are the ways I can think of right now. How much is needed and how you save need planning, and that's what we do. Do contact sateo7689@yahoo.com if you need so. 以上是我目前能想到的。至于需要多少钱以及如何储蓄则另需规划。而后者正是我们的工作。若是您有任何需要请联系sateo7689@yahoo.com。

Monday, February 29, 2016

091 Education fund in Foreign Currency

Wang pendidikan dalam matawang asing外币教育基金Education fund in Foreign Currency
Semenjak jatuhnya kadar pertukaran MYRUSD, ramai yang terfikir hendak menyimpan dalam matawang asing. Adakah anda perlu berbuat demikian?自从马币兑美元滑落后,人们开始思想储存外币存款的必要性。你是否需要呢?Ever since the drop of MYRUSD exchange rate, more and more people think it's wise to keep some savings in foreign currency. Do you need it?
Nyatalah ini penting untuk sesetengah orang terutamanya mereka yang rancang untuk wang pendidikan mereka. Kecualilah, mereka hanya ingin menghantar anak mereka untuk sambung belajar di Malaysia sahaja.对于某些人,尤其是正准备孩子教育基金的人,这个尤其重要。除非他原本就只打算让孩子在本地大学或学院深造。Well, it is important to some people especially those preparing for children's educations fund, unless a parents only planned to send their children to study tertiary education in local universities or colleges.
Mungkin seseorang ibubapa perlu menyediakan RM500k untuk anak mereka. Cara selama ini ialah simpan dalam RM dan tukar kepada matawang asing apabila masanya sampai.要送孩子出国读书,父母可能得准备RM50万。一般的做法是不停的存马币,然后在孩子出国时才兑换。Imagine this. It may take RM500k for a parents to send their child study abroad. The usual practice was to save and save in RM and convert to foreign currency when it's due.
Apabila matawang kita susut nilai, ibubapa tersebut akan merasai kerugian dari segi pertukaran matawang.当本国货币贬值时,该父母就感受到汇兑上的损失。When our currency depreciated, the parents will feel the pain of currency exchange loss.
Adakah kita mempunyai alternatif lain? Ya. Dengan terdapatnya syarikat insurans offshore, rakyat Malaysian sekarang boleh rancang wang pendidikan dalam USD, EUR atau GBP.那现在我们是否有其他选择呢?答案是肯定的。随着岸外保险公司的出现,大马人民可直接以美元,欧元或英镑准备教育基金。Do we have alternative now? Yes, of course. With the availability of offshore insurance companies, Malaysian can now plan education fund in USD, EUR or GBP.
Ibubapaboleh mulakan pelan insurans simpanan tetap 10 atau 15 tahun lebih awal. Contahnya, mereka sumbang USD500 selama 120 bulan, maka mereka akan mengumpul sebanyak USD60K dan juga pertumbuhan modal. Mereka boleh lupakan pertukaran matawang kerana kadar puratanya telah dibahagi-bahagikan dalam 10 tahun yang lepas.父母可以提前10或15年开始一个储蓄计划。若是每月供款USD500为其120个月,父母可累及USD6万再加上资本成长。货币兑换率就不会是一个问题因为他的平均兑换率已经在过去的10年里被均摊了。A parents can start a regular savings insurance plan 10 or 15 years well ahead. If he contributes USD500 a month for the next 120 months, he would have accumulated USD60K plus with the growth. And he can forget about the currency exchange because his average rate has been spread out within that 10 years.
Sekiranya anaknya tidak menghabiskan kesemua duit itu, maka dapatlah dia sedikit simpanan matawang asing. Alangkah bagusnya.如果孩子每有用完所有储蓄的话,也意味着父母又多了一笔外币存款。很好不是吗?If his child does not use up the amount, then he has extra money as foreign currency savings. How nice.
Perbezaan dengan unit trust matawang asing与外币基金的差别Difference with foreign currency unit trust
Sebelum ini saya pernah terangkan unit trust matawang asing. Bukankah ibubapa tersebut boleh simpan dala unit trust ini?这之前我曾介绍过外币信托基金。那父母亲可否通过这类基金大致同样目标呢?Before this I explained about foreign currency unit trust. Can't the parents save through this unit trust?
Kos pendidikan sesuatu negara adalah berkaitan dengan ekonomi negara itu. Bukan semua unit trust matawang asing boleh akses kepada negara-negara tersebut. Pelan insurans offshore mempunyai lebih akses dalam hal ini.一国的教育费是与该国的经济息息相关的。并不是所有外币基金都可投资到该国。相比岸外保险计划有较多的投资。Cost of education in a country is tighly related to its economy. Not all foreign currency unit trust has access to that particular company. Offshore insurance plan has more access in this aspect.
Satu lagi ialah, unit trust matawang asing tidak boleh terima simpanan bulanan secara potongan bank buat masa ini. Walaupun pelanggan boleh buat top up secara manual setiap bulan, is adalah terlalu banyak kerja. Untuk berjaya menyimpan wang pendidikan, prosesnya harus diotomatikkan untuk memastikan matlamat tercapai.另一点是外币信托基金暂不接受每月投资。顾客虽然可以每月手动投资,但毕竟太麻烦了。为了达致目标,整个动作还是自动化为妙。One more thing is foreign currency unit trust doesn't accept regular savings as of now. Although the client can do manual monthly top up, but it is still too troublesome. To achieve the goal, the process has to be automated.
---
---